S&P500 Daily Action Areas & Price Targets 14/9/26
S&P500 Daily Action Areas & Price Targets 14/9/26
***QUOTING ES1! FOR CASH US500 EQUIVALENT LEVELS, SUBTRACT POINT DIFFERENCE***
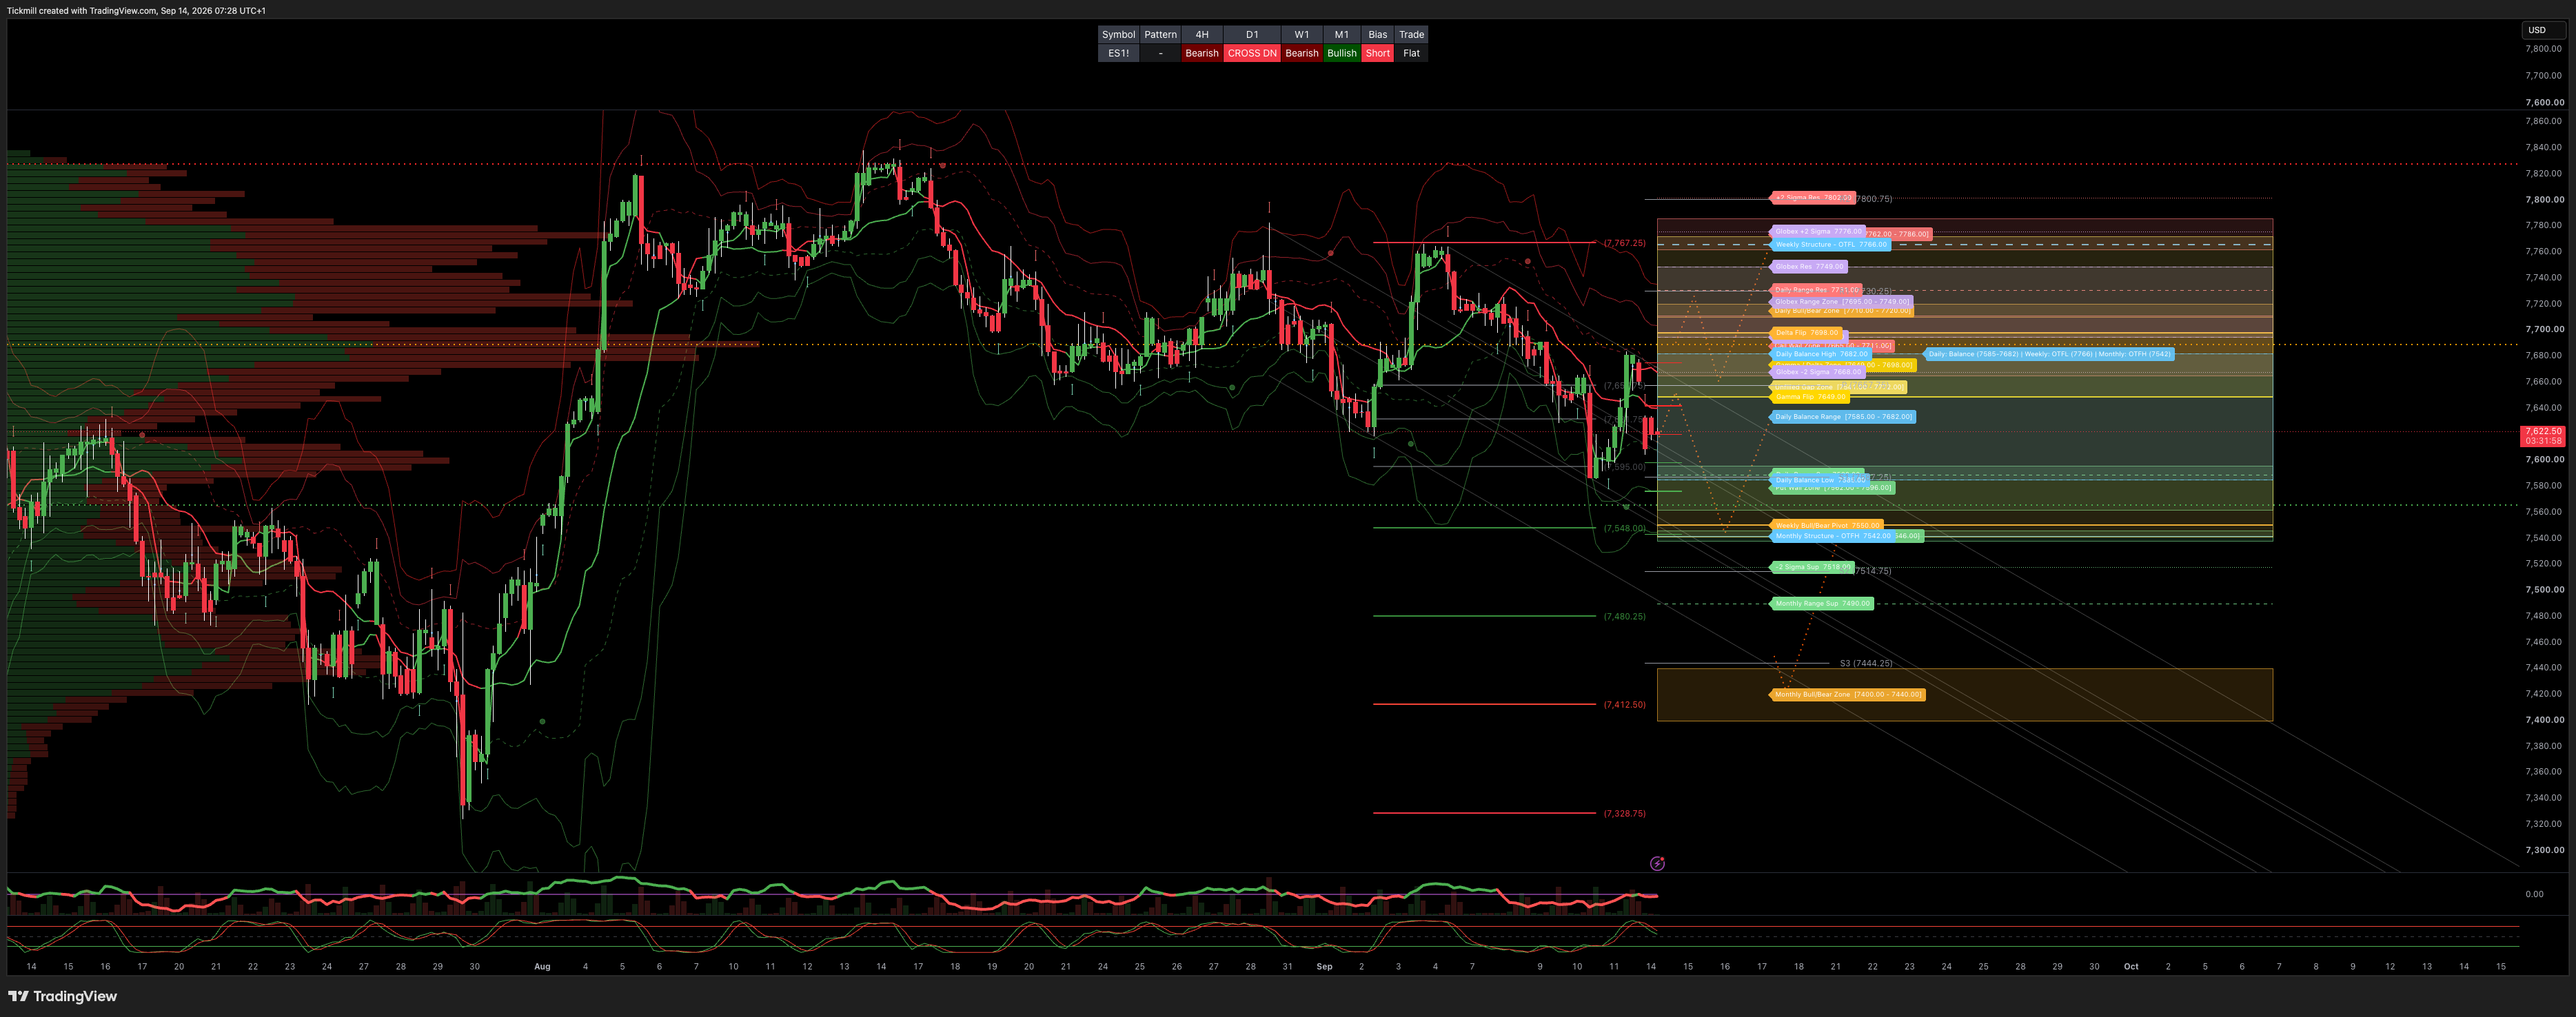
MONTHLY-WEEKLY& DAILY LEVELS
MONTHLY BULL BEAR ZONE 7440/7400
MONTHLY RANGE RES 7882 SUP 7490
WEEKLY BULL BEAR ZONE 7550
WEEKLY RANGE RES 7762/86 SUP 7538/46
DAILY BULL BEAR ZONE 7710/20
DAILY RANGE RES 7731 SUP 7589
2 SIGMA RES 7802 SUP 7518
GLOBEX RANGE RES 7749 SUP 7695
2 SIGMA RES 7668 SUP 7776
GAMMA FLIP 7649
DELTA FLIP 7698
PUT WALLS 7562/7596
CALL WALLS 7711/7665
UNFILLED GAPS 7541 - 7772
DAILY STRUCTURE - BALANCE - 7682/7585
WEEKLY STRUCTURE - OTFL - 7766
MONTHLY STRUCTURE - OTFH - 7542
VIX BULL BEAR ZONE 17.3 (VVIX / VIX) 5.21
PRIMARY TRADES & TARGETS
SHORT ON REJECT/RECLAIM DBBZ TARET DAILY RANGE SUP
LONG ON ACCEPTANCE ABOVE DBBZ TARGET DAILY RANGE RES
LONG ON REJECT/RECLAIM WBBZ TARGET
***ADDITIONAL SETUPS & TARGETS HIGHLIGHTED ON THE CHARTS***
(I FADE TESTS OF 2 SIGMA LEVELS ESPECIALLY INTO THE FINAL HOUR OF THE NY CASH SESSION AS 90% OF THE TIME WHEN TESTED THE MARKET WILL CLOSE ABOVE OR BELOW THESE LEVELS)
SPX PUT/CALL RATIO 1.23 (The numbers reflect options traded during the current session.) A put-call ratio below 0.7 is generally considered bullish, and a put-call ratio above 1.0 is generally considered bearish.
JHEQX Q3 Collar Short Call Cap: ~7,750 – 7,900 - Long Put Strike: ~7,050 – 7,100 (approx. 5% downside protection) Short Put Strike: ~5,950
DEC2025 OPEX to DEC2026 OPEX is 945 points giving us a range of [5889,7779]
Notes On Structure Implications
Balance: This refers to a market condition where prices move within a defined range, reflecting uncertainty as participants await further market-generated information. Our approach to balance includes favouring fade trades at the range extremes (highs/lows) while preparing for potential breakout scenarios if the balance shifts.
One-Time Framing Higher (OTFH): This represents a market trend where each successive bar forms a higher low, signalling a strong and consistent upward movement.
One-Time Framing Lower (OTFL): This describes a market trend where each successive bar forms a lower high, indicating a pronounced and steady downward movement.
GOLDMAN SACHS FICC & EQUITY TRADING DESK VIEWS
THE TAKE: MARKET WALKS A TIGHTROPE AS MARGIN FOR ERROR NARROWS
Investor anxiety remains high, characterized by net exposures pinned at the 6th percentile and the largest macro ETF shorting since Liberation Day. Concurrently, surface volatility appears suppressed—the VIX sits at ~15, 27 consecutive sessions have traded in <100bps bands, and the SPX 1-week straddle trades at just 130bps.
Macro assets have walked the line between a tipping point and status quo all summer. With key catalysts hitting the tape this week, the margin for error is narrowing rapidly.
FIVE KEY WEEKLY CATALYSTS & DESK FOCUS
Oil & Geopolitics (Brent >$109 / WTI >$100):
Crude is back at the center of market narrative. GS revised Brent/WTI forecasts higher last week under the assumption that Middle East shipping disruptions will persist through 2027. Ahead of Monday's talks in Oman, heavy hedging flows hit leisure names (airlines, cruise lines, retail). Notably, oil implied volatility remains at half the levels seen during previous crude spikes.
Fed Meeting (Wednesday Rate Hike Expected):
A rate hike on Wednesday is now both market consensus and the GS house expectation. GS Economics views this as a "forced hike" to manage market optics rather than a purely fundamental move. Counterintuitively, a "one-and-done" hike could calm market nerves by removing ambiguity for the remainder of 2026 and reinforcing Fed independence.
Japan & JGB Yields (10Y Near 3%):
Underappreciated in US markets, JGB 10-year yields near 3% make domestic Japanese fixed income competitive again ahead of this week's BoJ meeting. This risks shifting Japan from a structural buyer of global duration into a source of capital repatriation—removing a marginal buyer just as sovereign back-ends face supply pressure.
Bonds & Long-End Rates (10Y ~5.0% / 30Y >5.3%):
Rising long-end yields represent a primary constraint on high-multiple and long-duration equities. The average 30-year mortgage has crossed 7%, putting extra focus on this week’s $13B 20-year Treasury auction.
AI Volatility & Macro Dynamics:
Following Dario Amodei's weekend essay, market participants are grappling with the inflection in AI capabilities. AI infrastructure remains an omnipresent market factor—a known transformation with highly uncertain knock-on effects and adoption speed.
DESK FLOWS, POSITIONING & VOLATILITY MATRIX
Market Dimension | Current Level / Flow Metric | Historical Context / Percentile | Desk Observations & Tactical Insights |
Prime Brokerage (PB) Flows | Net Sold (Macro ETF Shorts) | Largest $ short selling since Liberation Day | Caution rules; short-side macro hedging is driving overall net supply. |
Sector Positioning (PB) | TMT Long Buying vs. Cyclical Supply | Largest 2-week TMT long buying since 2025 | Communacopia drove TMT demand; Cyclicals (Financials) aggressively sold by HFs. |
Cash Volumes (1M Avg) | Down ~40% from July Highs | Post-COVID style volume drop | Extreme volume decline amplifies 0DTE vol influence over cash index moves. |
Index Put Skew | Steepened sharply | Highest level since July | ATM vol flat, but skew bid; dealer long gamma to topside makes rallies harder to sustain. |
Sentiment Dislocation | AAII Bearishness at ATHs | AAIIBEAR implies VIX 25 (vs. actual VIX 15) | Deep disconnect between depressed surface vol and underlying investor anxiety. |
CTA Systematic Flows | Broken Short-Term Trends | Technical damage done across benchmarks | Marginal forced selling triggered across global equity indexes. |
CONVERTIBLE ISSUANCE & THEMATIC BASKETS
Convertible Bond Supercycle: 2026 is pacing as the highest convertible bond issuance year in market history, serving as a primary non-dilutive funding vehicle for the AI infrastructure buildout.
Featured Secular Trades:
Buy the Dip in AI Hardware (
GSTMTDAT): Fundamentals remain intact and institutional positioning has cleaned up significantly post-de-risking.Short Consumer Inertia (
GSXUSWCH): Short companies where consumer stickiness relies on switching friction rather than product differentiation, as agentic AI tools lower friction for consumers to change service providers.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% and 73% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!